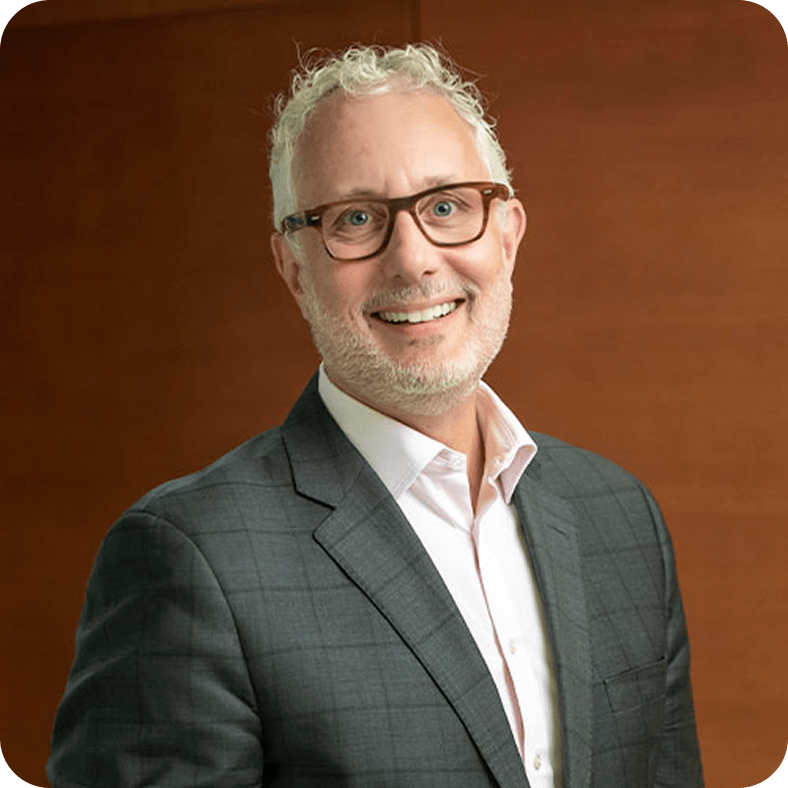
Michael: Hi everyone. This is Michael Zeuner, one of the managing partners at WE Family Offices. Thanks for listening. I’m joined today by Sam Sudame, our global head of macro.
And for those of you who are regular listeners, you’ll know we’ve been talking a lot about the developed market [inaudible]. We’ve been talking about the AI trade, we’ve been talking about our fairly benign view on capital markets, particularly equity markets going forward.
We’ve also got a little [into] our views on the fixed income markets, particularly U.S. Treasuries and where risks may be if we head into a higher-than-expected inflationary period.
And, you know, we’ve talked a lot about staying short on duration and not taking a lot of interest rate risk with U.S. bonds.
And today we’re gonna go in a little bit of a different direction about the fixed income space. We’re going to talk about a space that for most investors has really been off the radar screen, frankly, for good reasons historically. That’s the emerging market debt space.
And, you know, I’m sure most people listening to this podcast will remember the stories about Argentina — sort of exhibit A — as really a very dangerous [area] for fixed income investors.
But under the hood, what we’ve been seeing, and Sam’s been paying attention to it, is that all of a sudden in the last year, year and a half, we’ve started to see the returns in emerging market [debt] look relatively attractive, particularly when you compare it to U.S. government debt.
So I’d like to start, Sam, by just sort of laying the groundwork for what you’ve been observing, and then maybe we’ll talk a little bit about what that might mean for investors going forward.
Sam: Sure. Thank you for having me, Michael.
So, you know, what we’ve seen is that there have been improvements in emerging market fundamentals that have made their debt more resilient compared to the past.
So despite higher geopolitical risk this year, emerging market debt is outperforming U.S. Treasury bonds, high yield corporate markets and the Barclays Agg.
Now, in the past during times of higher geopolitical risk, emerging market debt declined more than other fixed income markets. So this year is particularly impressive.
So that really got the interest as to why is this happening? Of course, you mentioned some of it at the beginning. Investors might be scarred by past emerging market debt events, and historically this space has seen a great [deal of volatility/risk].
Michael: And Sam, I hear you on that. And it’s interesting, right? We should understand why this might be happening.
So give us your context for why this might be happening, but whether what’s happening — you know, as you and I always like to say — is fundamental, or driven more by emotion and sentiment, which is always a dangerous [thing].
Sam: So, you know, as we dig into those fundamentals, what we’ve been seeing is that the average quality of emerging markets is increasing at its best rate in the past 20 years.
Michael: How do you define quality, Sam?
Sam: So we’ll get into some of those different fiscal dynamics, about the governance in emerging markets.
So what we’ve seen right now is greater fiscal discipline, increased monetary credibility. So those stronger EM fundamentals and good yields are creating a favorable environment.
And now when we look at those factors or fundamentals versus the growth premium — because that was a headwind for many years as the growth premium fell as China began its multi-year economic [slowdown] — now that premium is starting to expand because China has stabilized and other emerging market countries are growing.
But the biggest single reason for the improvement: stronger fundamentals are being supported by better policy structures.
So more emerging market countries have instituted strong fiscal and monetary policy. The key driver of these fundamentals has been the credibility of emerging market policy.
So policy reform in the post-Great Financial Crisis period meant that many EM central banks entered that big global inflation shock from 2021 and 2022 with established inflation targeting, clearer communication practices, better operational independence from the government.
And that has led to better debt-to-GDPs, higher foreign exchange reserves and lower deficits than they had in the past and compared to the developed markets.
Michael: And when you look going forward, Sam, do those fundamentals look like they’re gonna hold, or are they sort of short-term things that are subject to changes?
Sam: Sure. So, you know, emerging markets have that inherent issue of governance, that their regimes are not as strong, so they are more subject to political changes.
But we’ve been seeing this now for many years, and what it has led to is much more discipline than what we’ve seen in the past.
So, for instance, on the whole, the debt-to-GDP for emerging market countries is around 60% compared to 100% in developed countries. And that’s because, by and large, they are running lower budget deficits that are more fiscally [disciplined].
They have gone [through] the historical crises — for instance, Latin America in the 1980s, the Asian debt crisis of the 1990s, [and] Argentina.
They have seen what has happened to their economies and their standard of living for their population when they ran poor policies. Now you’re seeing a much different regime.
Michael: So what I think I hear you saying, Sam, is that when you look at the positive returns, certainly relative to Treasuries, that you’re seeing in emerging market debt, you can make a case that it’s an interesting space for fixed income investors going forward.
What’s the opposite case, Sam? What would be the reason to stay cautious?
Sam: Well, emerging markets, just like we see in equity, are countries that are in a very high level of political, social and economic flux.
So as a result, risk can manifest itself very quickly in those markets for both debt and [equity]. They do not have rule of law, they might not have regimes that [inaudible].
But what you have seen is that in recent years, again, the better fiscal balances, the better debt-to-GDPs, better inflation dynamics, with yields compared to the West — with yields that are about 200 basis points higher than developed government bonds.
So we are [seeing] things that, when you turn to risk, look really attractive.
Michael: So I would take from that, Sam, a couple of [things].
One is that emerging market debt investment is not for the faint of heart.
Two is that no big bets, as we always like to say.
And three is, I’m guessing that you would believe that active managers can really demonstrate skill. Unlike in the [developed] markets, where it’s very difficult, in emerging market [fixed] income there’s likely a role for active [management].
Sam: Yes, active management is absolutely key to understand both the ability and willingness of emerging market countries to pay their debts. So it requires a lot of in-depth analysis of their economic and political structures.
But what emerging market debt also [does] is, you know, it is another tool in the toolbox. It does provide — it does generate income — and I think it is worth considering as part of a diversified income portfolio, just like emerging market equities are to an equity portfolio.
Michael: Okay. Well, thanks for that view, Sam. We appreciate it. And we’ll look forward to talking again soon.
Sam: All right. Thank you, Michael.